An iron condor through the 2008 crash, day by day
What happens to an iron condor when the market falls apart? Here is one SPX iron condor, opened on the real option prices of 2 September 2008 and followed every trading day until its expiry in October — the weeks of Lehman Brothers and the worst of the crash.
The condor on 2 September 2008
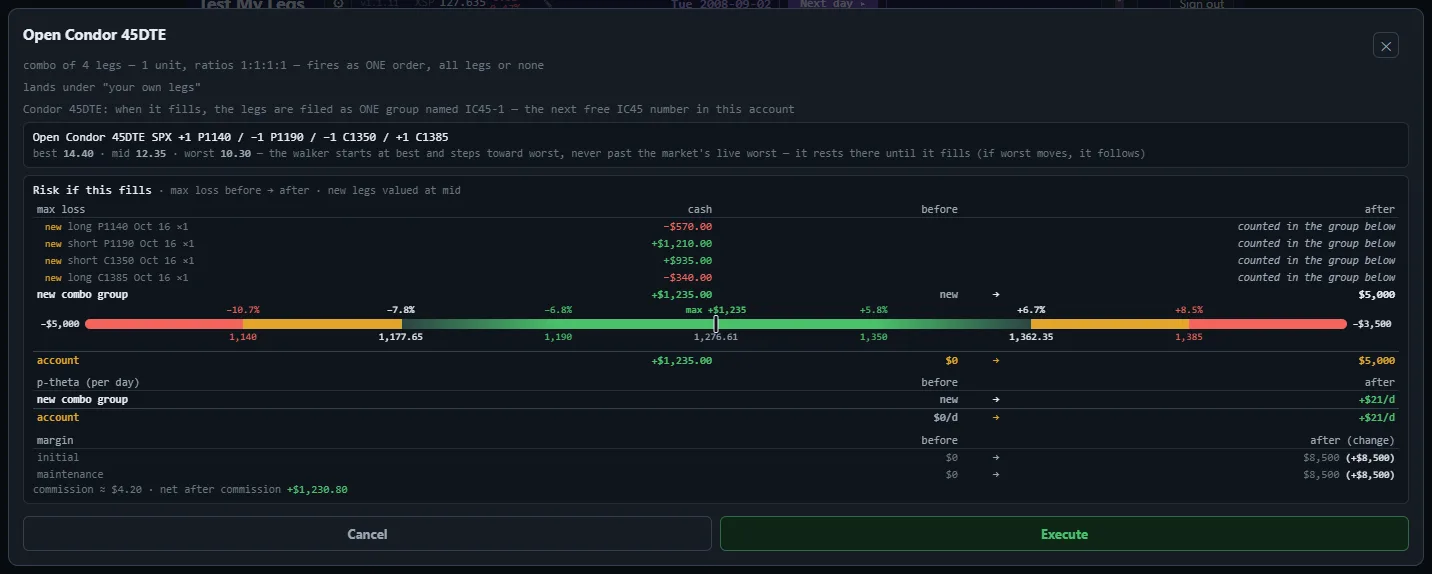
The test started on Tuesday 2 September 2008 with $100,000; SPX stood at 1,276.61. With +Strat → Condor 45DTE on SPX, the app solved four legs on the October 2008 expiry (last trading day 16 October, 44 days away):
| Leg | Strike | Delta | Bid – ask | Filled at |
|---|---|---|---|---|
| Buy put (wing) | 1,140 | 10.4 | 5.20 – 6.20 | 5.81 |
| Sell put | 1,190 | 19.5 | 11.30 – 12.90 | 11.99 |
| Sell call | 1,350 | 20.3 | 9.00 – 9.70 | 9.24 |
| Buy call (wing) | 1,385 | 9.8 | 3.00 – 3.80 | 3.51 |
The credit was 11.91 — $1,191 for one condor. The put side is 50 points wide, so the most it could lose is $5,000 less that credit. Notice how wide the bid–ask already was: 11.30 to 12.90 on the sold put.
Day by day
| Day | SPX | 1190 put (sold) | 1140 put (bought) | Condor P&L |
|---|---|---|---|---|
| Tue 2 Sep 2008 | 1,276.61 | 12.10 | 5.70 | −$45 |
| Mon 8 Sep | 1,266.02 | 12.10 | 5.30 | +$85 |
| Fri 12 Sep | 1,257.18 | 15.60 | 7.40 | +$2.50 |
| Mon 15 Sep (Lehman files) | 1,195.27 | 39.30 | 22.00 | −$672.50 |
| Wed 17 Sep | 1,161.09 | 58.10 | 35.60 | −$1,092.50 |
| Fri 19 Sep | 1,244.06 | 23.05 | 12.95 | −$110 |
| Mon 29 Sep | 1,115.16 | 91.20 | 60.20 | −$1,770 |
| Fri 3 Oct | 1,105.73 | 92.50 | 58.10 | −$2,260 |
| Mon 6 Oct | 1,049.39 | 143.90 | 101.80 | −$3,007.50 |
| Thu 9 Oct | 909.92 | 279.30 | 229.70 | −$3,777.50 |
| Mon 13 Oct | 1,013.20 | 177.35 | 128.25 | −$3,717.50 |
| Thu 16 Oct (expiry) | 937.67 | 251.10 | 201.10 | −$3,810 |
For two weeks nothing much happened. Then SPX fell through the sold put in a few days, bounced back above it on 19 September, and fell again. From 9 October both puts were deep in the money and the put spread was worth nearly its full 50 points, so the condor stayed close to its maximum loss whether SPX was at 886 or 1,013 — and on expiry day it was exactly there: −$3,810 ($5,000 width less the $1,190 credit). The call side expired worthless.
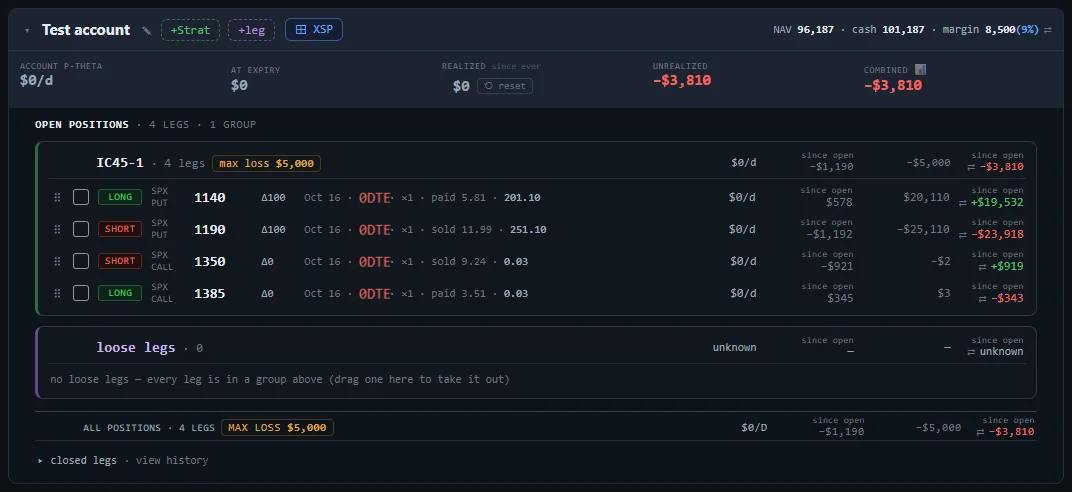
Held to expiry, the account finished at $96,186.80 — a loss of $3,813.20 with commissions, on a $100,000 account.
What this example shows
- The wings did their job: SPX fell 30% from the day the condor opened, yet the loss stopped at the width of the put spread. Without the bought put, the sold put alone was worth 251.10 on expiry day.
- Size is what decides how much a crash costs. One condor with a $5,000 width was 5% of this account.
- There were chances to act — the bounce on 19 September brought the condor back near −$110. Go back to that day in your own test and try closing or rolling.
This example is one real run in Test My Legs on the recorded SPX option prices of September and October 2008. It is a backtest: it shows what happened on those days, not what will happen next.
Try it on another date yourself. Test My Legs is free: pick a past day and step through it.
Start now